

Simple Checkbook Ledger
by Teelu Apps
3.4
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.4
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
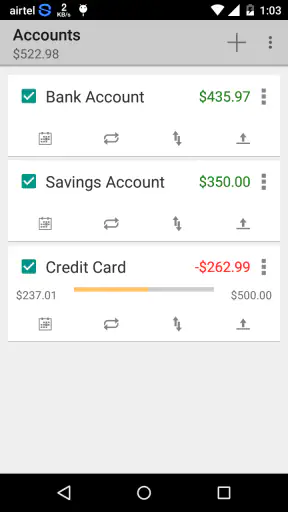
When I want to understand where my money is going without handing every transaction to a full banking suite, I prefer a simple ledger that stays focused on recording activity. That is the role Simple Checkbook Ledger tries to fill. It is a free finance app from Teelu Apps, built around the everyday habit of entering income, spending, and account movements so the balance in the app reflects what I believe is available.
I approached it as I would any checkbook replacement: start with an account, record a few ordinary transactions, move money between accounts, and then check whether the resulting balance is useful enough to guide a real decision. The app has been available since August 3, 2016, and its current version is 3.5. It is a mature, narrowly focused tool rather than a broad personal-finance platform, which is both its appeal and its main limitation.
From an empty ledger to a usable money routine
I find a checkbook-style app most useful when I treat the first setup as a small routine, not a one-time data dump. Starting with one account and a balance I have checked against reality gives later entries a dependable reference point, while a brief review helps me catch slips before they shape a spending decision. That foundation makes it easier to judge how the ledger holds up during busier weeks.
Starting with the right expectation
The store summary describes the app as a way to manage accounts with ease, while its short description calls it Simple Checkbook. Those phrases set a fair expectation: this is best approached as a digital register, not as a replacement for online banking, tax software, or a complete household budgeting system.
That distinction matters before entering anything. A register works only when I treat it as a record that I maintain. If I expect automatic financial discovery, extensive spending analysis, or a bank dashboard that stays current without my involvement, I am looking in the wrong place. If I want to know the balance after I have entered a purchase, a deposit, or a transfer, the focused design makes more sense.
The app is listed under Finance and is rated for Everyone, so it is approachable for a wide range of users. It requires iOS 11 or later, which is worth checking before trying to install it on an older device. The app is free to start, with in-app purchases priced at $1.99 per item. That makes it easy to test the basic workflow before deciding whether any optional purchase fits the way I use it.
Creating a dependable starting point
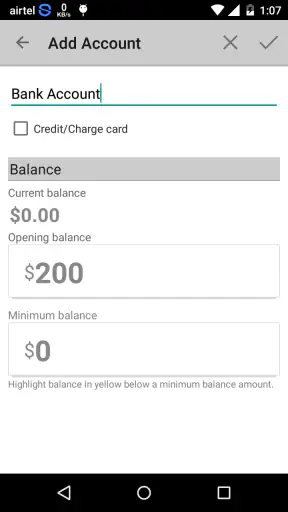
The first useful task is not entering every historical transaction. It is establishing a trustworthy opening balance. I would begin with the current amount in one account, then add only the transactions that still need to clear or affect that amount. Starting with a clean point prevents old activity from turning the ledger into a reconstruction project.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is one of the less obvious lessons with a checkbook-style app: accuracy is usually lost at the beginning, not at the end. If the opening figure is wrong, every later balance can look orderly while still being wrong. I recommend checking the actual account balance first, choosing a clear starting date, and keeping pending items separate in my own routine until they are reflected in the account.
For someone managing several accounts, I would set them up one at a time rather than entering everything in one sitting. A checking account, a savings account, and a shared household account have different purposes. Keeping those purposes distinct makes later transfers easier to understand and reduces the temptation to treat all available money as one pool.
Recording an ordinary day
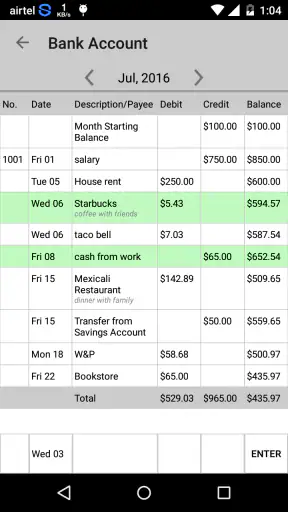
A realistic test is a normal day rather than a dramatic financial event. I might receive a paycheck, buy groceries, pay for transportation, and move a small amount into savings. The useful outcome is not a colorful report; it is a running balance that helps me answer a practical question: can I safely spend from this account before the next deposit?
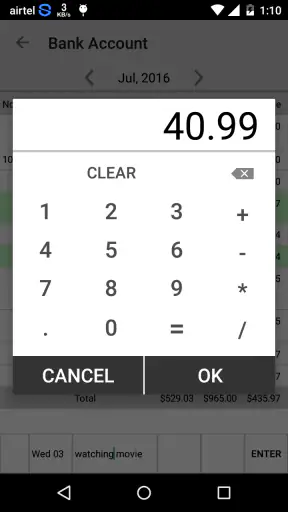
I would enter the paycheck first, then record each purchase close to the time it happens. That order is not required for every person, but it gives me a clear audit trail when I later compare the ledger with the account. For card purchases that have not settled, I would use a consistent personal rule: either record them immediately as part of my available-money calculation or wait until they post, but never switch methods casually.
The strongest habit here is recording transactions before the balance becomes a problem. A checkbook ledger is most helpful when it prevents an unpleasant surprise, not when it is used afterward to explain one. I found that entering small purchases matters because several modest expenses can change the answer to a spending decision even when none of them feels important alone.
Handling transfers without confusing income and spending
Moving money between accounts deserves special attention. A transfer from checking to savings is not new income and not household spending. It changes where the money sits. In a practical workflow, I would enter the outgoing side and the receiving side as one connected movement whenever the app’s account structure allows it, then check both balances afterward.
This handoff is where a simple ledger can become misleading if I treat every entry as a purchase. A transfer recorded as an expense makes checking look lower for the wrong reason and can distort any later review of spending. Conversely, recording only the deposit into savings leaves checking overstated. The safe approach is to verify the two account balances after the movement rather than trusting a single total.
The same care applies to reimbursements. If a friend pays me back for a meal, I would not automatically treat that payment as regular income. I would record it in a way that preserves the connection to the original outlay in my own notes or categories, depending on how I organize the ledger. This keeps the account balance accurate without making my spending habits look artificially low.
Using the ledger before making a decision
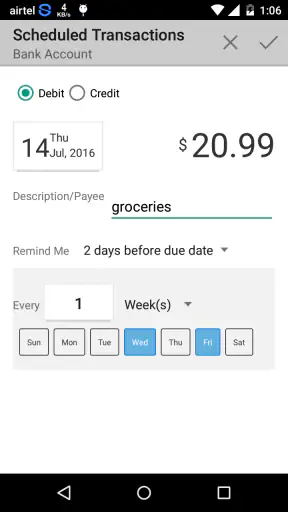
The best everyday use is a quick decision at the point of spending. Imagine I am considering a larger purchase near the end of the month. The bank balance may look sufficient, but several card charges, a scheduled bill, and a transfer to savings may already be committed. I would open the ledger, review those entries, and calculate what remains after the obligations I have already recorded.
That workflow is more useful than checking a raw bank balance because it includes my intentions. It is also more honest: the answer is only as good as the transactions I entered. If I forgot a bill or have not recorded a recent purchase, the app cannot correct the gap for me.
For a student, a freelancer, or someone managing a small number of personal accounts, this can be enough structure to reduce guesswork. It is particularly suitable for people who like writing down transactions and want a phone-based alternative to paper. It is less suitable for someone who wants the app to discover spending automatically or build a detailed financial picture with minimal input.
The handoffs that determine whether it works
A financial ledger sits between several real-world sources: receipts, card notifications, bank statements, cash payments, and memory. The app can hold the record, but I still have to move information from those sources into it. That handoff is the central responsibility of using this kind of tool.
My most reliable routine would be to enter a transaction immediately when it is easy, then do a short review at the end of the day for cash purchases and anything I postponed. Once a week, I would compare the ledger with the account activity. This is not glamorous, but it catches forgotten small payments before they accumulate into a confusing difference.
Receipts are especially useful for cash spending. A bank statement cannot remind me about cash, while the ledger cannot know that cash was spent unless I enter it. I would therefore keep a temporary note during a busy day and transfer those items into the app later, using the same wording each time. Consistent descriptions make old entries easier to recognize when I am checking a discrepancy.
Another handoff involves other people. If a partner or family member spends from a shared account, the ledger is only complete if those transactions reach my workflow. That may mean agreeing on who records purchases, or reviewing the account together. The app cannot solve a shared-account communication problem, so households should decide on that responsibility before relying on the displayed balance.
Checking the result instead of trusting it blindly
After several days of entries, I would judge the app by the quality of the answer it gives me. Can I see what has changed since the last check? Can I distinguish a purchase from a transfer? Can I reconcile the displayed balance with the actual account without starting over? Those questions are more important than whether the interface feels impressive.
A good result is a balance I can use with confidence because I know how it was built. The app is valuable when it gives me a current working figure for an account and a visible history of the choices that produced it. That is a modest result, but it directly addresses the problem a paper checkbook has traditionally handled.
It also encourages a useful separation between recorded money and expected money. I would not treat an anticipated paycheck as available until it arrives, and I would not ignore a known bill simply because it has not posted. The ledger can support that cautious thinking as long as I use clear descriptions and review pending commitments in my own process.
Where the flow becomes uncomfortable
The main friction is manual maintenance. Every missed transaction weakens the next balance, and the weakness may not become obvious until I try to reconcile the account. People who dislike entering purchases, frequently use several cards, or need automatic synchronization may find this approach too demanding. A bank’s own app or a more automated money manager will usually be a better fit for them.
There is also a limit to what a checkbook workflow can explain. Recording a transaction tells me that money moved, but it does not automatically turn that history into a complete plan for debt reduction, investment allocation, or long-term financial forecasting. I can use the record as a foundation for those decisions, but I should not mistake the foundation for the whole structure.
Cash-heavy users face another trade-off. The app can be useful for cash if I record each payment, yet cash is also the easiest area to forget. Someone who wants a completely automatic record will be frustrated. Someone willing to enter cash purchases may appreciate having one place to keep the account balance honest.
Shared finances can expose the same weakness. If several people make transactions but only one person updates the ledger, the displayed result will lag behind reality. In that situation, a collaborative finance tool may be more appropriate, especially if simultaneous visibility and automatic updates matter more than a simple personal register.
Who should use it, and who should choose something else
I would recommend this app to a person who wants a straightforward account register, prefers manual control, and is willing to spend a few minutes maintaining it. It can also suit someone moving away from paper who does not need a large collection of financial dashboards. The focused approach keeps the daily task understandable: enter the movement, check the balance, and reconcile periodically.
I would skip it in favor of a banking app when my priority is live account information from the financial institution. I would choose a budgeting platform when I need automatic categorization, household collaboration, detailed goals, or broad spending analysis. I would also look elsewhere if I need a strong record for business bookkeeping, because personal checkbook tracking is not the same as formal accounting.
The app’s average rating is 3.4 from around 2.5 thousand ratings, with roughly 1.2 thousand written reviews. I read that as a sign to keep expectations practical: the concept is useful, but a simple ledger will not satisfy every type of finance user. Its audience is narrower than the audience for an all-purpose money manager.
My final workflow recommendation
If I were setting this up for a friend, I would start with one account and a verified opening balance. I would record a full week of activity, including small cash purchases, then compare the result with the account. Only after that test would I add more accounts or consider an optional purchase. This exposes the real question quickly: will the person maintain the ledger consistently?
I would also create a fixed review point, such as the end of a shopping day or the same evening each week. The exact schedule matters less than making it repeatable. During the review, I would look for three things: transactions that were forgotten, transfers that were entered on only one side, and upcoming obligations that should influence the available balance.
Simple Checkbook Ledger has passed my basic test as a focused finance app because its value comes from a clear input-to-outcome path. I enter what happened, pass that information through a personal checking routine, and get a balance that can guide the next decision. The trade-off is equally clear: its simplicity saves attention only when I supply the discipline.
With over 100 thousand installs, it has found a substantial audience for this old-fashioned but still useful method. Teelu Apps keeps the idea centered on account management rather than turning it into an oversized financial system. I would recommend trying the free version to anyone who wants a digital checkbook and accepts manual entry. For users seeking automation, shared tools, or deep analysis, another finance app will probably deliver a smoother overall flow.
Pros
- Simple layout makes daily income and expense entries quick.
- Supports multiple accounts for separating personal and business finances.
- Running balances help track available funds after every transaction.
- Useful for users who prefer manual control instead of automatic bank syncing.
- Lightweight design generally works well on older Android devices.
Cons
- Manual entry can become time-consuming for frequent transactions.
- Limited automation compared with full-featured budgeting apps.
- Reports may feel basic for users who need detailed financial analysis.
- No automatic bank connection means balances require regular updating.
- The interface may look dated compared with newer finance applications.
FAQs for Simple Checkbook Ledger
What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and monitor personal financial transactions in a straightforward way. You can enter deposits, withdrawals, payments, and other adjustments, then review your running balance and transaction history. It is especially useful for people who want a lightweight checkbook register without the complexity of full budgeting or investment applications.
Does Simple Checkbook Ledger connect to my bank account automatically?
Simple Checkbook Ledger is primarily intended for manual transaction tracking rather than automatic bank synchronization. You generally enter transactions yourself, which gives you direct control over the information recorded in the ledger and can help avoid sharing banking credentials with a third-party service. Before downloading, users who require automatic imports should check the current app description and supported features.
Can I use Simple Checkbook Ledger for more than one account?
The app may support separate ledgers or account records, depending on the version and platform release, allowing users to keep checking, savings, cash, or other balances organized independently. However, account limits and available management tools can vary. It is worth reviewing the latest store listing to confirm whether multiple accounts, transfers, categories, or account-specific reports are included.
Is Simple Checkbook Ledger suitable for detailed budgeting and financial planning?
Simple Checkbook Ledger is best viewed as a transaction register and balance-monitoring tool, not necessarily as a complete personal finance suite. It can help you understand where money is being recorded and maintain an accurate running balance, but it may not provide advanced budgets, bill reminders, investment tracking, debt planning, or extensive visual reports. Users wanting those features should compare alternatives.
Is my financial information safe when using Simple Checkbook Ledger?
Because a checkbook ledger can contain sensitive details about purchases, income, and account balances, privacy should be considered before use. Review the app’s current privacy policy, permissions, backup options, and data-storage practices in the Google Play Store or Apple App Store. Avoid entering passwords, PINs, or complete banking credentials, and use device security features to protect locally stored records.

Simple Checkbook Ledger
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via apps.teelu@gmail.com, visit https://teeluapps.blogspot.com, or review their https://sites.google.com/view/freecheckbook/home.










